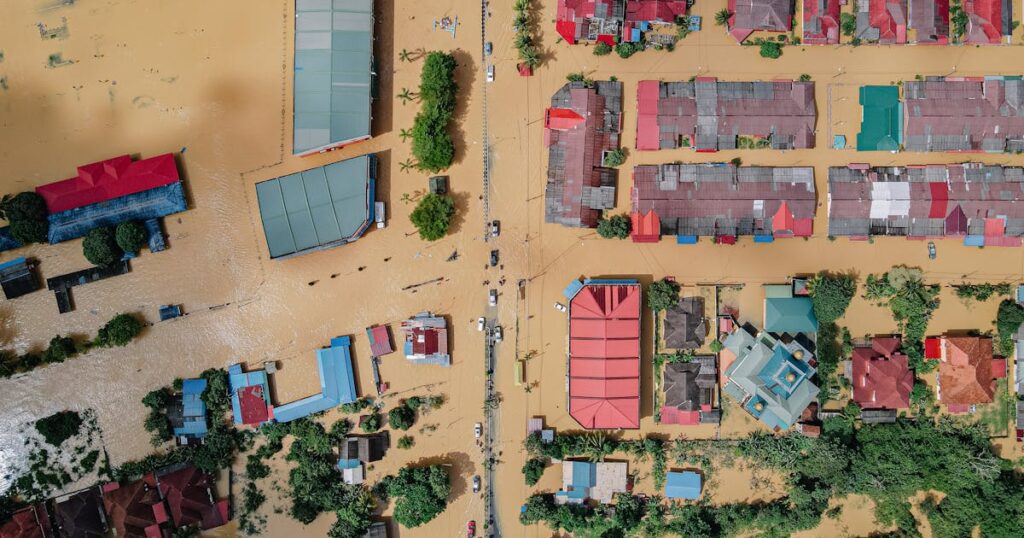
Flood insurance requirement table
Flood insurance requirements and flood risk are related, but they are not the same thing.
| Question | What it tells you | Next step |
|---|---|---|
| Is the lender requiring flood insurance? | The property is likely in a mapped high-risk flood zone for loan purposes. | Confirm the flood zone, policy timing, and escrow impact before closing. |
| Is the home outside a high-risk zone? | Insurance may not be required, but flooding can still happen. | Check local drainage, elevation, prior flooding, and optional policy cost. |
| Did maps or risk change? | Premiums and requirements can shift after map updates or lender review. | Ask for documentation and compare it with FEMA/local records. |
This is general homeowner education. Confirm requirements with your lender, insurer, and current flood map/property data.
Quick answer: flood insurance is usually required when a federally backed mortgage is tied to a property in a high-risk FEMA flood zone. Outside that setup, it is often not legally required, but that does not mean the risk is low. The mistake is confusing “not required” with “safe to ignore.”
Need the bigger insurance framework first? Start with the Homeowners Insurance Guide.
| If your situation is… | Required? | What usually controls it | Best next move |
|---|---|---|---|
| Mortgaged home in a FEMA Special Flood Hazard Area | Usually yes | Lender rules tied to federal flood requirements | Ask for the current flood zone and required coverage amount |
| No mortgage, but home is in a flood-prone area | Usually no legally | Your own risk tolerance and replacement-cost exposure | Price flood coverage before deciding to self-insure |
| Mortgage outside a high-risk zone | Often no | Lender discretion and property-specific factors | Do not assume low mapped risk means no practical flood risk |
| Condo or HOA situation | It depends | Master policy, unit-level risk, and lender requirements | Verify what the association covers versus what you still need |
Flood requirement route
- You have a federally related mortgage in a high-risk zone: assume required until documents prove otherwise.
- You are outside mandatory zones: decide based on loss exposure, not false comfort.
- You are buying in Florida or another coastal market: verify flood and homeowners coverage as separate problems.
Risk flags homeowners miss
- “Not required” is not the same as “safe to skip.”
- Flood maps, local drainage, and actual storm behavior do not always line up cleanly.
- Waiting until a storm is close can be too late because of policy waiting periods.
August 2026 source check: FloodSmart still says flood insurance is required for a property in a Special Flood Hazard Area when there is a government-backed mortgage, and that some banks can require coverage outside high-risk zones. FloodSmart also now frames low- and moderate-risk zones more bluntly: every zone has flood risk, and 1 in 3 flood insurance claims come from low- and moderate-risk zones.
When flood insurance is usually required
The classic trigger is simple: the home is in a high-risk mapped flood zone and the loan is backed by a federally regulated or federally insured lender. In that situation, the lender usually requires flood insurance as a loan condition.
That means the practical decider is often not city government or your insurer. It is the lender, reacting to flood maps and federal lending rules.
Scenario routing: what applies to you
| Scenario | What matters first | What homeowners often miss | Recommended next step |
|---|---|---|---|
| Buying in a mapped flood zone | Required coverage to close | Flood premium can change true affordability fast | Get the premium quote before finalizing the purchase budget |
| Already own the home and lender says coverage is required | Map determination and loan status | Force-placed insurance can be worse and more expensive | Provide proof of acceptable coverage quickly |
| Not in a high-risk zone | Actual property vulnerability, not just map label | Many floods happen outside the strictest zones | Model the loss before you dismiss the premium |
| Cash buyer | Pure risk decision | No lender requirement does not remove repair risk | Decide whether you can truly absorb a major flood loss |
What flood insurance is not
Standard homeowners insurance usually does not cover flood. That is the core reason this decision matters. If rising water or external inundation is the loss path, the ordinary homeowners policy is usually not the backstop owners think it is.
Worked examples
Example 1: Required for closing
A buyer is under contract on a home in a Special Flood Hazard Area using a conventional mortgage from a federally regulated lender. The lender requires flood insurance before closing. The buyer can dislike it, but the loan does not fund cleanly without meeting the requirement.
Example 2: Not required, still financially exposed
A homeowner outside the highest-risk mapped zone assumes flood is somebody else’s problem. A heavy rain event and drainage failure push water into the house. Their standard homeowners policy does not respond the way they hoped. “Not required” turned out to be meaningless at claim time.
Example 3: Force-placed coverage pain
A lender determines the property needs flood coverage and the borrower does not provide proof fast enough. The lender force-places a policy or equivalent protection. The cost is ugly, the coverage is not chosen by the homeowner, and the whole thing is avoidable with earlier action.
Watch-outs
- Flood maps are not the whole story: mapped risk and real-world drainage risk are related, not identical.
- Lender requirement is not the same as personal need: a lender may not require it and the house may still be vulnerable.
- Affordability math changes: flood premiums belong in the monthly carrying cost, not as an afterthought.
- Waiting periods and timing matter: do not assume you can buy coverage at the exact moment water risk becomes obvious.
- Condo owners can get lazy here: the HOA master policy may not protect your interior improvements and contents the way you think.
How to decide if you should carry it even when not required
- Confirm the flood zone, but do not stop there.
- Look at site drainage, nearby water, elevation, and local flooding history.
- Estimate the dollar pain of even a moderate flood event.
- Compare that risk with the annual premium, not with wishful thinking.
- If you are buying, include the premium in your affordability decision before closing.
Best next-step utility
| If you need to decide… | Read this next | Why |
|---|---|---|
| What homeowners insurance covers versus excludes | What Does Homeowners Insurance Actually Cover? | Flood is one of the biggest exclusions people misunderstand |
| How to read your policy and endorsements | How to Read Your Homeowners Insurance Policy | You need the exclusions and endorsements section, not just the declarations page |
| Whether the house budget is getting distorted by hidden costs | The Real Cost of Owning a Home | Flood premiums belong in the true carrying-cost math |
Bottom line
Flood insurance is sometimes required by the lender. Much more importantly, it is sometimes necessary whether the lender requires it or not. The expensive mistake is letting the bank make your entire risk decision for you.
If this, do this next
- You need the plain-English version of the choice: read do you need flood insurance next.
- You are buying or reviewing coverage now: pull the FEMA map, lender conditions, and two real quotes.
- You still think homeowners insurance may cover flood: read what homeowners insurance actually covers before assuming that gap is handled.
Best next step: Compare what homeowners insurance covers with how to read your policy, then pressure-test the monthly cost in the real cost of owning a home.
Free OwnerHacks checklist
Home Insurance Coverage Gap Checklist
A practical homeowner checklist for spotting deductible, flood, roof, water, and coverage gaps before renewal or a claim.
Official resources and reference points
This page is homeowner education, not a property-specific appraisal, legal opinion, tax advice, or lender/carrier instruction. Use these to verify the coverage language, complaint path, and Florida-specific rules before you act on a denial letter, underwriting scare, or policy summary.
Why this article is worth trusting
Caleb Hollis reviewed this page. He reviews homeowner education on home value logic, cost realism, Florida housing questions, and decision quality.
See the reviewer profile and editorial team profile for who does what. OwnerHacks publishes homeowner education, not property-specific appraisal work, legal advice, tax advice, lending advice, or insurance advice.
OwnerHacks updates articles when rules, costs, or homeowner decision factors materially change. If something looks outdated, use our contact page and we will review it.
Free homeowner checklist
Before surprise costs hit, budget the first year.
Grab the First-Year Homeowner Cost Checklist for insurance, taxes, utilities, repairs, moving costs, tools, and setup expenses that often show up after closing.
Get the free checklist